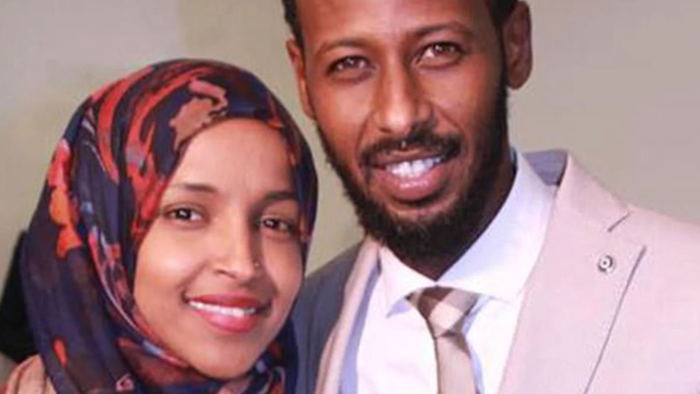
"Something's Going To Happen": DHS Chief Says Lefty Ilhan Omar "Married Her Brother", Floats Deportation
Key takeaway
""Something's Going To Happen": DHS Chief Says Lefty Ilhan Omar "Married Her Brother", Floats Deportation" — BullBear's AI rates this story as a bearish (negative) signal for markets, with a market-impact score of 38 out of 100. Reported by ZeroHedge on September 13, 2026. The call is verified against the actual 24-hour price move on BullBear's public conviction ledger.
Catch the next bear flag
Telegram alerts when our AI scores a story 80+/100 impact (~1-3 per day, no spam).
Verified 30d hit rate 42.0%.
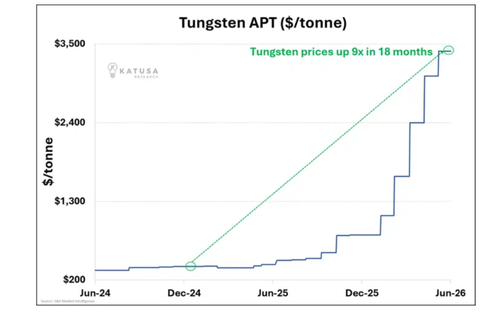
Heightened resource nationalism across key tungsten producers is tightening supply chains and amplifying price volatility in the broader base metals market. The United States’ restriction on scrap imports, the United Kingdom’s state‑backed financing of a new mine, Zimbabwe’s export ban, and Vietnam’s contemplation of export limits collectively signal a shift toward protectionist policies that constrain global availability. Such moves reinforce concerns about geopolitical risk and reinforce a narrative of constrained commodity flows, dampening bullish sentiment that had been buoyed by earlier demand forecasts. The tightening environment dovetails with macro‑level themes of de‑globalisation and supply‑side fragility, prompting investors to reassess exposure to metals reliant on politically sensitive jurisdictions. Consequently, confidence in the sector erodes, prompting a more cautious risk appetite and potentially prompting capital rotation toward less geopolitically exposed assets as well as longer‑term strategic allocations.
Developments in the Gulf that bring Iranian officials to the United Arab Emirates and hint at a potential Oman‑based shipping arrangement signal a thaw in regional diplomatic friction, which could smooth trade corridors for energy and commodities. A more stable geopolitical environment tends to lower the risk premium on Middle‑East assets, encouraging capital inflows into equities and sovereign bonds linked to the area. The prospect of a formalized maritime link may also boost logistics and shipping firms that serve the Persian Gulf, adding a sector‑specific catalyst. In the broader macro context, reduced tension aligns with global efforts to secure energy supplies and mitigate supply‑chain disruptions, reinforcing expectations of steadier oil flows. Consequently, investor confidence is likely to improve, prompting a modest shift toward higher‑risk, higher‑return positions in the region while maintaining a cautious stance on broader market volatility.